Summary
Highlights
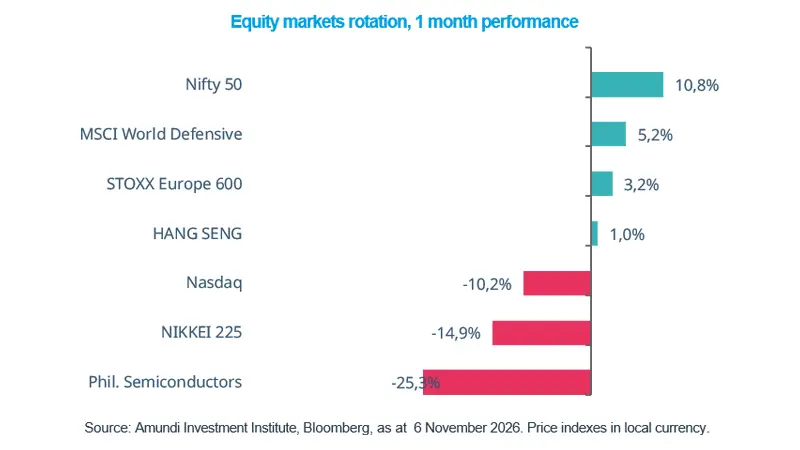
Over the past few weeks, we have seen a rotation away from US tech due to scrutiny of the massive capex and results of the US mid terms.
By contrast, global defensive sectors and some regions such as India posted gains.
This rotation underscores the importance of a global, diversified approach that avoids concentration in US tech.
In this edition
The US midterm elections delivered a Democratic sweep of Congress, and markets responded with a dramatic rotation. The shift was swift and decisive: investors moved out of high-growth, technology-heavy businesses into areas of the market that had long been overlooked. The clearest losers were semiconductor and AI-linked stocks, as investors worried about increased regulation in the sector and demanded more clarity on the massive spending plans of large technology companies. The Japanese market, heavily exposed to the global technology supply chain, was also caught in the sell-off. By contrast, European equities held their ground, and the Indian market posted strong gains, reflecting a broader search for alternatives to the US. Defensive global equities — think utilities, healthcare, and consumer staples — quietly outperformed. The message from the markets seems to be that the era of undisputed US technology dominance is being questioned.
Key dates
China Exports, Japan Current Account Balance, US CPI |
Japan PPI, India CPI, US Initial Jobless Claims |
US PPI, India Trade Balance |
Read more